Credit sales sound simple until you try to calculate them from real business records. On paper, a credit sale is any sale where the customer receives goods or services now and pays later. In real life, it hides inside invoices, payment terms, sales returns, discounts, allowances, partial payments, accounting software reports, and the occasional spreadsheet named “FINAL-final-v7.xlsx.” Fun times.
Knowing how to calculate credit sales matters because it tells you how much revenue your business has generated from customers who still owe money. This number affects accounts receivable, cash flow planning, receivables turnover, bad debt estimates, working capital, and even how confidently you can sleep at night without dreaming about unpaid invoices tap dancing across your desk.
In this guide, we will break down three practical ways to calculate credit sales: using the direct net credit sales formula, deriving credit sales from total sales, and estimating credit sales through accounts receivable analysis. Each method works best in a different situation, so the smartest approach depends on the records you have available.
What Are Credit Sales?
Credit sales are sales made to customers who do not pay immediately at the time of purchase. Instead, the seller issues an invoice and allows the customer to pay later, often under terms such as net 15, net 30, or net 60. For example, if a design agency completes a $5,000 branding project and gives the client 30 days to pay, that $5,000 is a credit sale.
Credit sales are different from cash sales. A cash sale happens when payment is collected right away, whether by cash, credit card, debit card, bank transfer, or another immediate payment method. A credit sale creates accounts receivable because the customer owes the business money.
Businesses track credit sales because they reveal how much revenue depends on future collection. A company can appear busy and profitable, yet still struggle with cash if customers are slow to pay. That is why credit sales are closely connected to accounts receivable management, collection policies, credit terms, and cash flow forecasting.
Why Calculating Credit Sales Matters
Calculating credit sales is not just a bookkeeping chore. It is a financial health check. If your credit sales are growing faster than collections, your business may be selling more but collecting less. That can create a cash crunch, even when the income statement looks cheerful.
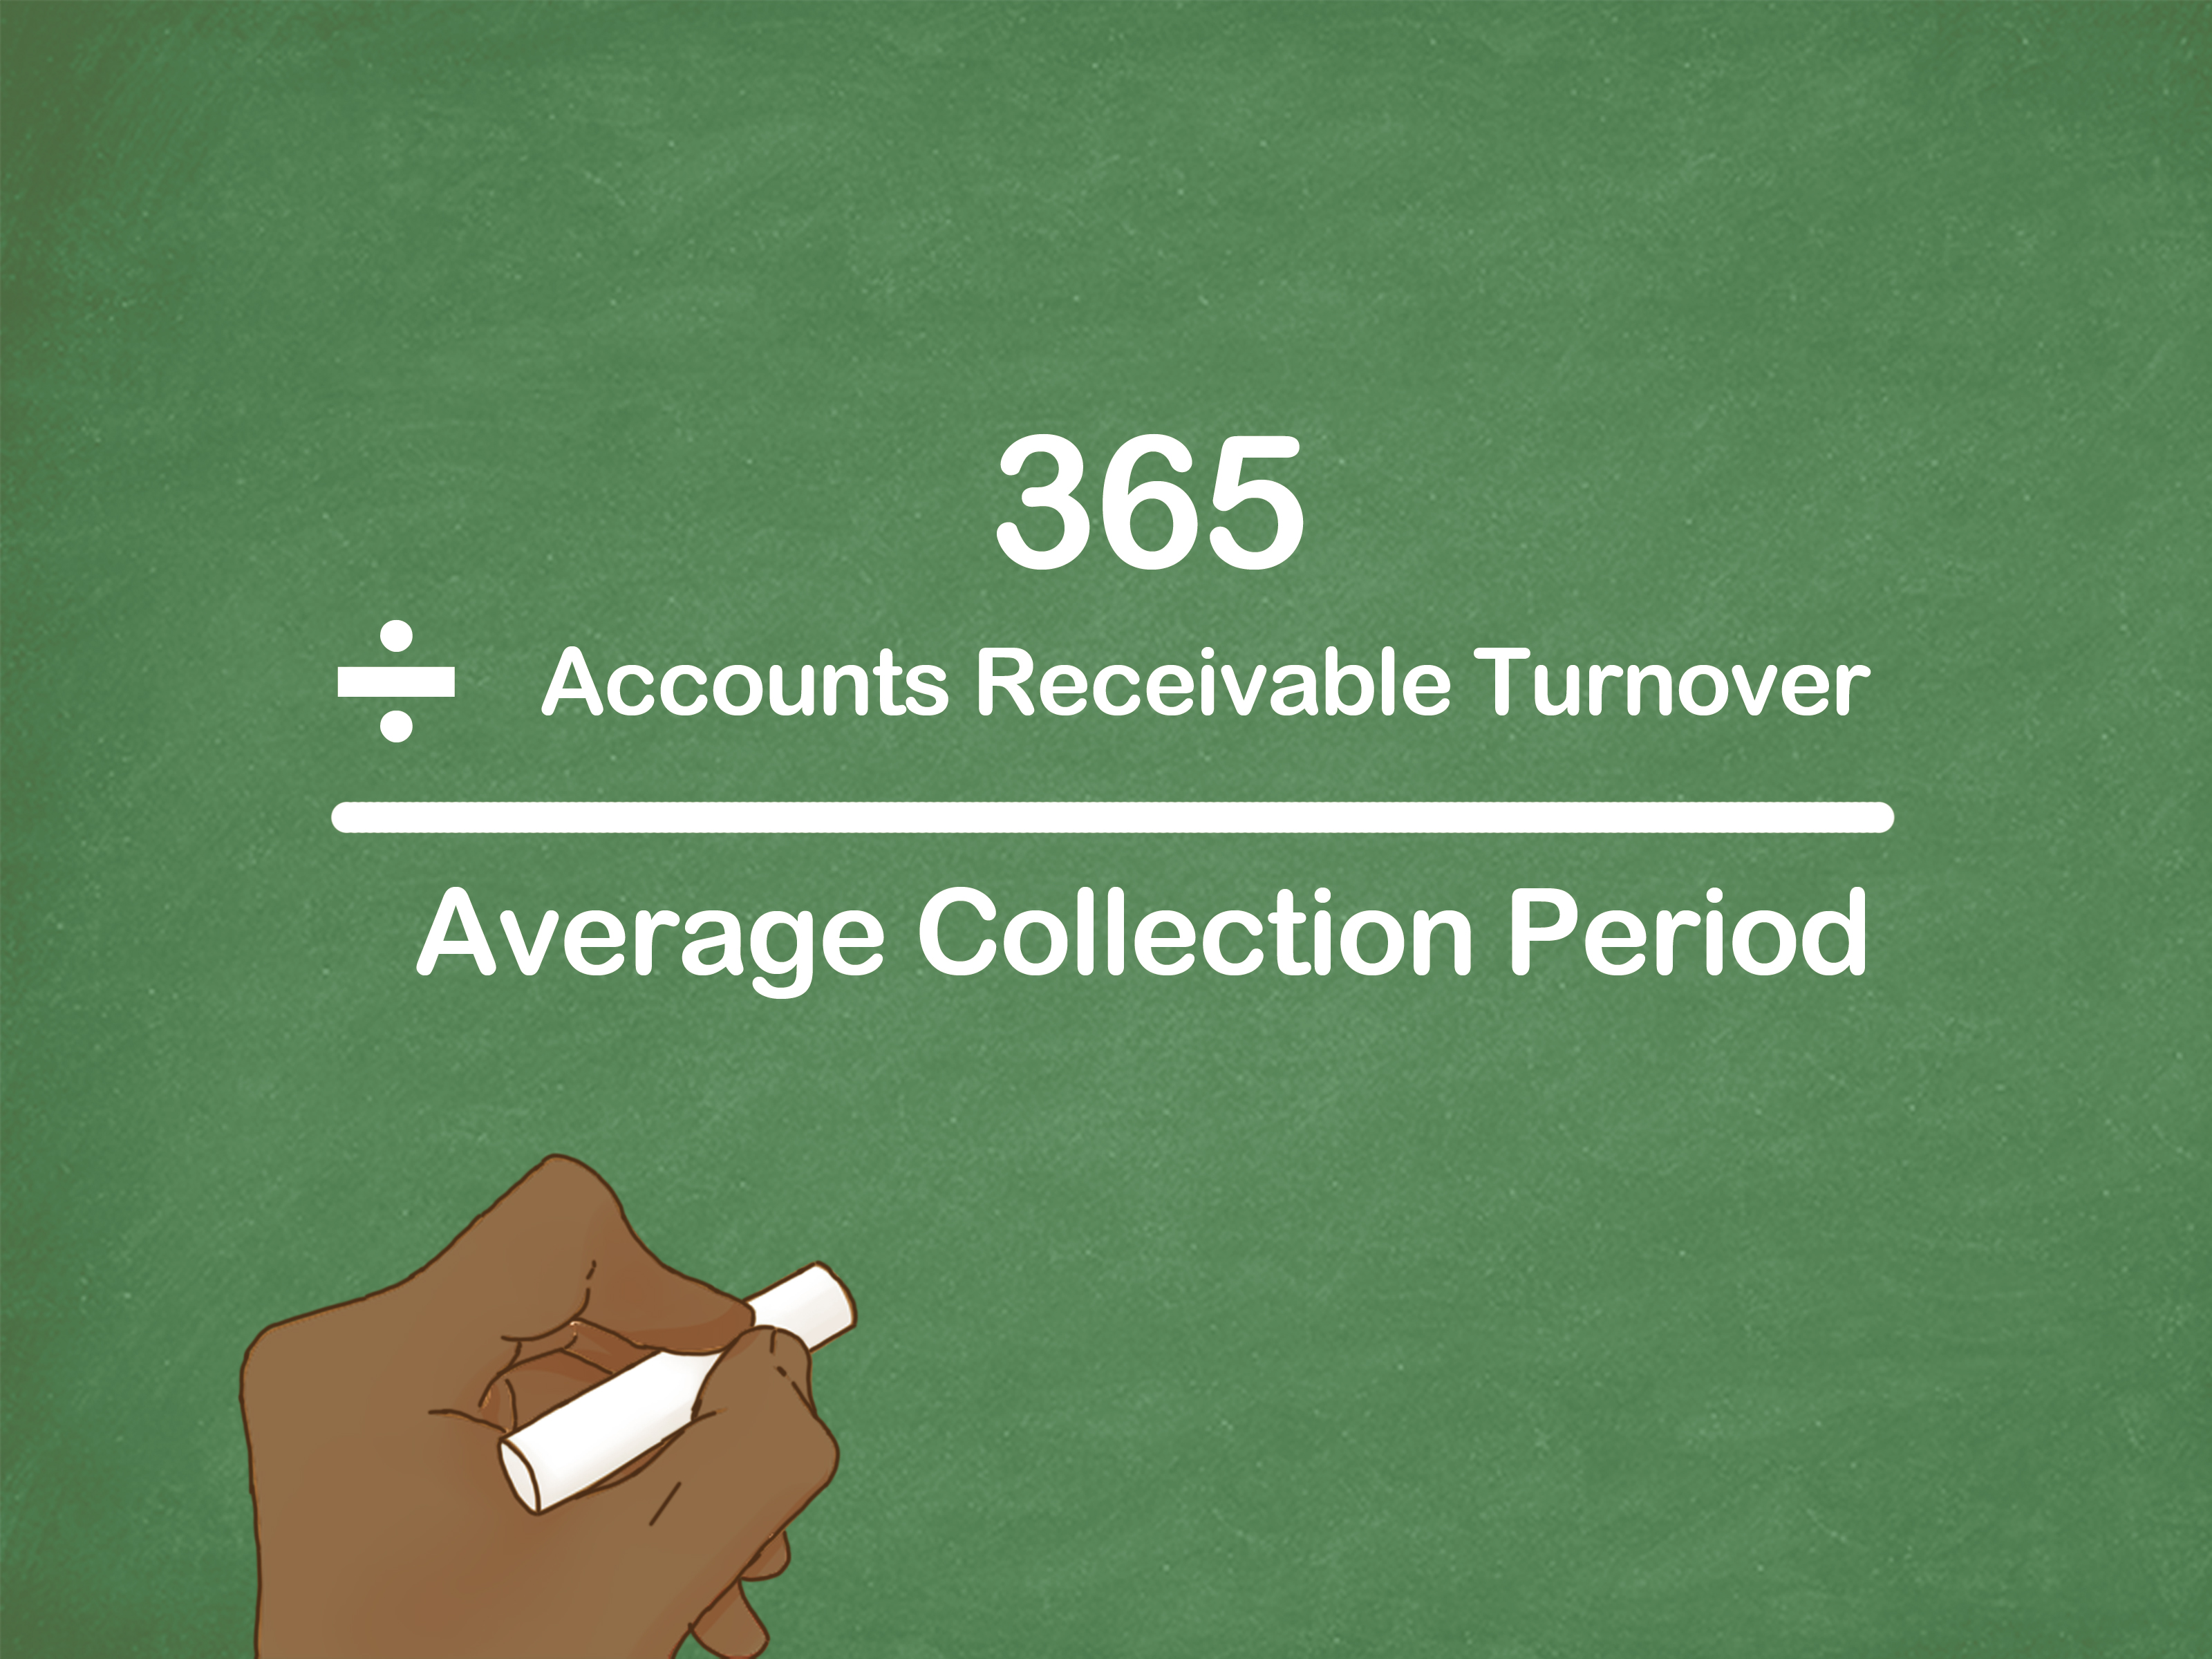
Credit sales also help calculate the accounts receivable turnover ratio, which measures how efficiently a business collects money from customers. The basic formula is:
Accounts Receivable Turnover = Net Credit Sales / Average Accounts Receivable
A higher turnover ratio usually means customers are paying faster. A lower ratio may suggest weak collection practices, overly generous credit terms, poor customer screening, billing delays, or invoices that have gone on vacation without telling anyone.
Credit sales also support bad debt estimation. Many businesses estimate doubtful accounts as a percentage of credit sales, especially when historical data shows that a predictable portion of invoiced sales may never be collected.
Way 1: Calculate Net Credit Sales Directly
The Formula
The most direct way to calculate credit sales is to start with total credit sales and subtract deductions related to those credit sales.
Net Credit Sales = Total Credit Sales – Sales Returns – Sales Allowances – Sales Discounts
This method is best when your accounting system clearly separates credit sales from cash sales. It is commonly used by businesses that issue invoices, track accounts receivable, and maintain separate sales accounts for credit transactions.
What Each Part Means
Total credit sales are all sales made on account before deductions. These are invoices issued to customers who will pay later.
Sales returns are amounts deducted because customers returned products or canceled part of a sale. For example, if a customer returns $1,000 worth of goods from a credit purchase, that amount reduces credit sales.
Sales allowances are price reductions given after the sale, often because of defects, shipping issues, damaged items, service problems, or billing corrections. The customer keeps the product or service but pays less.
Sales discounts are reductions offered to encourage early payment. For instance, terms such as “2/10, net 30” mean the customer gets a 2% discount if payment is made within 10 days; otherwise, the full invoice is due in 30 days.
Example of the Direct Method
Imagine a small wholesale business had the following numbers for April:
- Total credit sales: $80,000
- Sales returns: $4,000
- Sales allowances: $1,500
- Sales discounts: $2,500
The calculation is:
Net Credit Sales = $80,000 – $4,000 – $1,500 – $2,500 = $72,000
So, the company’s net credit sales for April were $72,000. This is the amount of credit revenue the company expects to collect after reducing the original invoices for returns, allowances, and discounts.
When This Method Works Best
This method is the cleanest and most accurate when your books are organized. If your accounting software separates credit invoices from cash receipts, this formula gives you a reliable net credit sales figure. It is especially useful for wholesalers, B2B service providers, manufacturers, agencies, contractors, and companies that regularly invoice clients.
The only catch is that you must avoid mixing cash sales with credit sales. If a customer pays immediately, that sale does not belong in credit sales, even if the payment was made by credit card. A credit card transaction may feel like “credit” to the buyer, but from the seller’s perspective, it is usually treated more like an immediate payment, minus processing fees.
Way 2: Derive Credit Sales From Total Sales
The Formula
Sometimes a business knows total sales but does not have a separate credit sales report ready. In that case, you can derive credit sales by subtracting cash sales from total sales, then adjusting for credit-related deductions.
Net Credit Sales = Total Sales – Cash Sales – Credit Sales Returns – Credit Sales Allowances – Credit Sales Discounts
This method is useful when your income statement shows total sales, but you need to identify the portion made on credit.
Example of the Total Sales Method
Suppose a furniture store reports these monthly figures:
- Total sales: $150,000
- Cash sales: $60,000
- Returns from credit customers: $5,000
- Allowances given to credit customers: $2,000
- Early payment discounts: $1,000
First, subtract cash sales from total sales:
$150,000 – $60,000 = $90,000
Then subtract the deductions connected to credit customers:
Net Credit Sales = $90,000 – $5,000 – $2,000 – $1,000 = $82,000
The store’s net credit sales are $82,000.
Why Matching Deductions Matters
The biggest mistake with this method is subtracting all returns, allowances, and discounts without checking whether they came from cash sales or credit sales. If a cash-paying customer returned a product, that return should not reduce credit sales. It should reduce net sales, yes, but not net credit sales.
This detail may sound small, but it can distort accounts receivable analysis. If you understate credit sales, your receivables turnover ratio may look weaker than it really is. If you overstate credit sales, your collection efficiency may look better than reality. Accounting is not exactly a comedy club, but it does have a cruel sense of humor when numbers are matched incorrectly.
When This Method Works Best
This method works well for small and medium-sized businesses that have mixed sales channels. Retailers, repair shops, online sellers, clinics, and service businesses may receive immediate payments from some customers while invoicing others. If total sales are easy to find but credit sales require extra sorting, this method gives a practical path.
To make this calculation easier in the future, businesses should tag transactions by payment type inside their accounting software. Labels such as “cash sale,” “card sale,” “invoice sale,” and “credit customer” can save hours of detective work later. Your future self will appreciate it, possibly with coffee.
Way 3: Estimate Credit Sales Using Accounts Receivable
The AR Turnover Approach
The third way to calculate credit sales is to use accounts receivable data. This is especially helpful when you know your receivables turnover ratio and average accounts receivable, but you do not have a clean credit sales figure.
The standard receivables turnover formula is:
Accounts Receivable Turnover = Net Credit Sales / Average Accounts Receivable
You can rearrange it to solve for net credit sales:
Net Credit Sales = Accounts Receivable Turnover × Average Accounts Receivable
Example of the AR Turnover Method
Assume a company has an accounts receivable turnover ratio of 8 and average accounts receivable of $25,000.
Net Credit Sales = 8 × $25,000 = $200,000
This means estimated net credit sales are $200,000 for the period.
How to Calculate Average Accounts Receivable
Average accounts receivable is usually calculated by adding beginning accounts receivable and ending accounts receivable, then dividing by two.
Average Accounts Receivable = (Beginning AR + Ending AR) / 2
For example, if beginning AR is $20,000 and ending AR is $30,000:
Average AR = ($20,000 + $30,000) / 2 = $25,000
This average smooths out the balance so one unusually high or low day does not dominate the analysis.
The AR Roll-Forward Approach
You can also estimate gross credit sales using the movement in accounts receivable. A simplified accounts receivable roll-forward looks like this:
Ending AR = Beginning AR + Credit Sales – Collections – Write-Offs – Credit Memos
Rearranged, the formula becomes:
Credit Sales = Ending AR – Beginning AR + Collections + Write-Offs + Credit Memos
This method is useful when you have reliable data for beginning AR, ending AR, customer collections, write-offs, and credit memos. However, it requires careful bookkeeping because timing differences can create confusion. For example, a payment received after month-end should not be counted as a collection for the previous month.
When This Method Works Best
The AR method is best for analysis, reconstruction, and financial review. Accountants, bookkeepers, lenders, and business owners may use it when sales records are incomplete but receivables data is available. It is also useful when checking whether reported credit sales make sense compared with collections and outstanding invoices.
However, it should be used carefully. If accounts receivable includes non-trade receivables, employee advances, tax refunds, loans, or other unrelated balances, the calculation may be misleading. Only trade receivables from normal customer sales should be included when analyzing credit sales.
Credit Sales vs. Net Sales: Do Not Mix Them Up
Net sales and net credit sales are related, but they are not the same. Net sales include all sales after returns, allowances, and discounts. Net credit sales include only credit sales after credit-related returns, allowances, and discounts.
Here is the difference:
Net Sales = Gross Sales – Sales Returns – Sales Allowances – Sales Discounts
Net Credit Sales = Credit Sales – Credit Sales Returns – Credit Sales Allowances – Credit Sales Discounts
If every sale is made on credit, net sales and net credit sales may be nearly the same. But if the business has both immediate payments and invoiced sales, the two numbers can differ significantly.
Common Mistakes When Calculating Credit Sales
Counting Credit Card Payments as Credit Sales
A customer using a credit card does not automatically create a credit sale for the business. In most cases, the seller receives payment from the card processor quickly, so the sale is not treated as accounts receivable from the customer. Credit sales refer to sales where the customer owes the business directly.
Ignoring Sales Discounts
Early payment discounts reduce the amount collected from credit customers. If discounts are not subtracted, net credit sales may be overstated.
Mixing Cash Returns With Credit Returns
Returns from cash customers should reduce net sales, but not net credit sales. Keep deductions matched to the type of sale that created them.
Using Ending AR Instead of Average AR
When calculating accounts receivable turnover, average accounts receivable is usually more meaningful than ending AR alone. Ending AR can be unusually high or low depending on billing cycles, seasonality, or a few large invoices.
Forgetting Bad Debt and Write-Offs
Bad debt write-offs do not always reduce net credit sales directly, but they matter when analyzing collection performance. A company can have strong credit sales and weak collections if too many customers fail to pay.
Practical Example: Comparing All Three Methods
Let’s say a business wants to calculate net credit sales for the quarter. It has the following data:
- Total credit invoices issued: $120,000
- Credit returns: $6,000
- Credit allowances: $2,000
- Credit discounts: $1,500
Using the direct method:
Net Credit Sales = $120,000 – $6,000 – $2,000 – $1,500 = $110,500
Now suppose the same business only knows total sales of $180,000 and cash sales of $60,000. It can derive credit sales like this:
Total Sales – Cash Sales = $180,000 – $60,000 = $120,000
Then subtract credit-related deductions:
$120,000 – $6,000 – $2,000 – $1,500 = $110,500
Finally, suppose average accounts receivable is $27,625 and receivables turnover is 4 for the quarter:
Net Credit Sales = 4 × $27,625 = $110,500
In this clean example, all three methods lead to the same answer. In real business records, they may not match perfectly because of timing differences, misclassified transactions, write-offs, or incomplete data. When the results differ, investigate the source of the difference instead of politely pretending the spreadsheet did not just cough.
How to Improve Credit Sales Tracking
The best way to calculate credit sales accurately is to set up your accounting system correctly from the beginning. Separate cash sales from invoice sales. Use clear customer accounts. Record returns, allowances, discounts, credit memos, and write-offs consistently. Reconcile accounts receivable regularly. Review aging reports every month.
Businesses should also define credit policies. Who qualifies for credit? What payment terms are allowed? When does a late invoice trigger a reminder? When should credit privileges be paused? These policies help prevent credit sales from turning into “hope sales,” which are not recognized under any accounting standard, but are painfully familiar to many business owners.
Experiences and Practical Lessons From Calculating Credit Sales
One of the most useful lessons about credit sales is that the formula is often easier than the data. Many business owners understand the math quickly, but the real challenge is finding clean, reliable numbers. A company may have invoices in one system, payments in another, returns in email threads, and discounts tracked by someone named Brian who “has a spreadsheet somewhere.” The calculation becomes much easier when the sales process is organized before the month closes.
In practice, the direct method is usually the most trustworthy. When a business issues invoices through accounting software and records returns and discounts properly, net credit sales can be calculated with confidence. This is why bookkeepers often encourage businesses to stop using vague sales categories. A single account called “Sales” may feel simple at first, but it becomes a problem when management wants to know how much revenue came from credit customers, how much came from immediate payment, and how much was reduced by returns.
Another experience worth noting is that credit sales can look exciting while cash flow quietly suffers. A business might celebrate a big month of invoiced sales, only to realize that several customers will not pay for 45 or 60 days. Payroll, rent, inventory, software subscriptions, and tax obligations do not always wait that long. This is why net credit sales should be reviewed together with collections, accounts receivable aging, and days sales outstanding. Sales are good. Collected sales are better. Collected sales before the electric bill is due are poetry.
Small businesses often discover problems when they compare credit sales with accounts receivable aging. If net credit sales are increasing but the over-60-day receivables balance is also growing, the company may be extending credit too freely. This does not always mean customers are dishonest. Sometimes invoices are unclear, purchase order numbers are missing, billing contacts changed, or the company forgot to send reminders. A surprisingly large amount of “bad payment behavior” starts with messy communication.
Another practical lesson is to review discounts carefully. Early payment discounts can be helpful because they encourage faster collections, but they should not be offered casually. A 2% discount may sound tiny, but if margins are thin, it can make a noticeable difference. Businesses should compare the cost of the discount with the benefit of receiving cash sooner. If cash flow is tight, the discount may be worth it. If customers would have paid early anyway, the company may simply be giving away revenue with a smile and a tiny financial sigh.
Returns and allowances also deserve attention. A high level of returns may reveal product quality problems, shipping errors, misleading descriptions, or weak customer expectations. A high level of allowances may suggest that the business is frequently negotiating after the sale. When calculating credit sales, these deductions are not just accounting adjustments; they are operational clues. They tell you where revenue is leaking.
For growing companies, the best habit is to review net credit sales monthly. Compare them with cash collections, average accounts receivable, AR turnover, and bad debt trends. This turns a basic formula into a management dashboard. Instead of asking, “Did we sell more?” the business can ask better questions: “Did we sell to customers who pay?” “Are our terms too generous?” “Are invoices being sent quickly?” “Are discounts improving cash flow?” Those questions lead to stronger decisions.
The most important experience is this: credit sales are not automatically good or bad. They are a tool. Used wisely, they help a business win larger customers, build relationships, and grow revenue. Used carelessly, they create cash pressure and collection headaches. The goal is not to avoid credit sales entirely. The goal is to calculate them accurately, monitor them consistently, and make sure the business is not accidentally acting like a bank with worse paperwork.
Conclusion
Calculating credit sales helps a business understand how much revenue comes from customers who pay later. The three main methods are direct calculation from credit sales, deriving credit sales from total sales, and estimating credit sales through accounts receivable analysis. The direct formula is usually the most accurate when records are clean. The total sales method is useful when cash and credit sales must be separated. The accounts receivable method is valuable for analysis, reconstruction, and financial review.
The key is consistency. Match deductions to the right sales type, separate credit sales from cash sales, use average accounts receivable for turnover analysis, and review credit sales alongside collections. A business that tracks credit sales well has a clearer view of revenue quality, customer payment behavior, and future cash flow. In other words, it knows not just what it sold, but what it is likely to collect. That is where accounting stops being paperwork and starts being power.
Note: This article is for educational and business-writing purposes. For official financial reporting, tax filings, audits, or complex accounting issues, consult a qualified accountant or financial professional.